A Comprehensive Analysis of Factors Influencing Financial Performance Through Institutional Trust in Manggarai Regency's Local Government
DOI:
https://doi.org/10.22437/qqtsae54Keywords:
Budget Transparency, Financial Management Capacity, Organizational Accountability, Public Sector Financial Performance, Institutional TrustAbstract
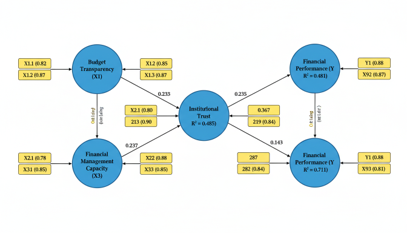
Purpose: This study aims to examine the impact of Budget Transparency, Financial Management Capacity, and Organizational Accountability on Public Sector Financial Performance, with Institutional Trust acting as an intervening variable on Local Government of Manggarai Regency.
Research Design and Methodology: The research employs the Partial Least Squares (PLS) method, which allows for the analysis of complex relationships among variables. Data were gathered through a survey using a questionnaire distributed to 120 respondents involved in financial management at the Manggarai Regency Government.
Findings and Discussion: The findings reveal that Budget Transparency, Financial Management Capacity, and Organizational Accountability have a significant direct effect on the financial performance of the local government. Furthermore, Institutional Trust plays a vital role as a mediator, strengthening the relationship between independent variables and financial performance. The study highlights that transparency in budget management, strong financial management capacity, and high organizational accountability are crucial for enhancing financial performance at the regional level. Additionally, the public's trust in the institution is essential in reinforcing these factors’ impact.
Implications: The study's results suggest that local governments should prioritize transparency in budget processes, invest in improving financial management systems, and foster accountability within organizations to improve financial performance.